 Karen Lopez
Most people who skip pet insurance for a young, healthy dog make that decision because nothing’s gone wrong yet. That’s exactly when they should be buying it.
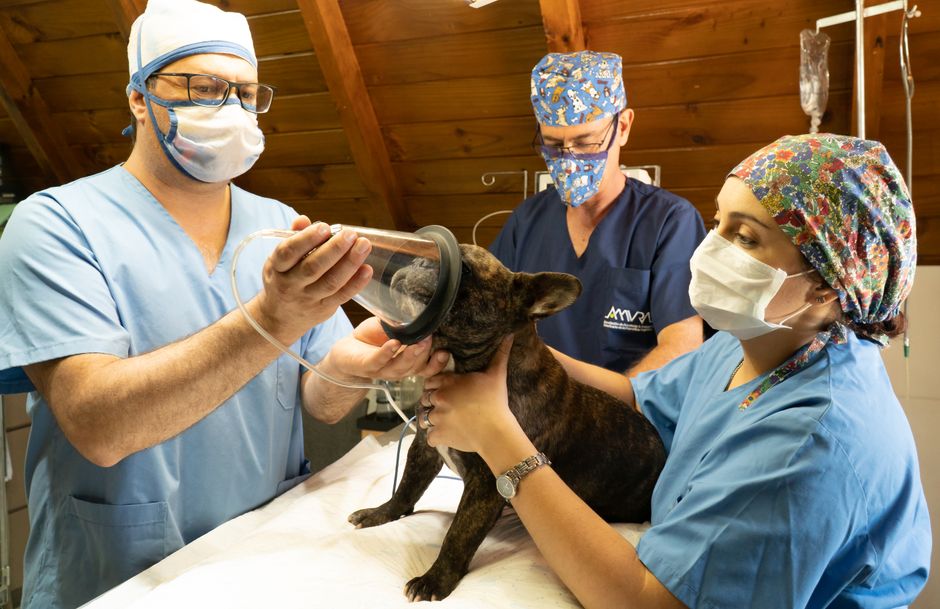
I came into this question with real skepticism. After 13 years as a vet tech, I’ve watched owners pay premiums for years and feel burned when they never actually used their policy. But I’ve also watched a 3-year-old Labrador eat a corn cob and rack up a $4,200 emergency surgery bill on a random Tuesday in October. The family had canceled their policy two months earlier because “he’s so healthy, it feels like a waste.” Two credit cards later, they learned different.
So here’s the real answer about pet insurance for young, healthy dogs, not the version where I list pros and cons and tell you to decide.
The Math People Get Wrong
Most people frame the insurance question like this: add up premiums paid over a few years, compare it to what they’ve claimed, and call it a loss if premiums exceed claims.
That’s not how insurance works.
You’re not buying a savings account. You’re buying protection against a risk. A reasonable policy for a young, medium-sized dog in most U.S. cities costs somewhere between $35 and $65 a month depending on breed, deductible, and reimbursement percentage. Let’s say $50. That’s $600 a year. Over three years of a perfectly healthy dog with zero incidents, you’ve paid $1,800 and gotten nothing.
Except you bought something real. You bought protection against what statistically happens to a lot of dogs, just not yours yet. The AVMA has documented for years that one in three pets will need unexpected veterinary care each year. For dogs specifically, foreign body ingestion, cruciate ligament tears, and skin conditions are visits that routinely break the $2,000 barrier before surgery estimates even come through.
A TPLO surgery for a blown knee in the backyard runs between $3,500 and $7,000 depending on your region and the surgeon. It’s not a freak accident. Labs, golden retrievers, rottweilers, mixed breeds, do this regularly, often before age 5.
Here’s the reframe: don’t ask “did insurance pay off so far?” Ask “could I write a $5,000 check tomorrow without wrecking my finances?” If yes, you might genuinely not need insurance. Most people can’t.
Why Young Is Actually the Right Time to Buy
This is what surprises most people. Younger dogs are better candidates for insurance than older ones, not because they’re more likely to get sick right now, but because of how underwriting actually works.
Pet insurance policies almost universally exclude pre-existing conditions. If your dog already has a documented health issue before you buy the policy, that issue isn’t covered. A young dog who develops hip dysplasia at age 2 and gets insured at age 3 will likely have that excluded. A dog insured at 10 weeks old would have it covered (assuming the policy was active before symptoms appeared). Same dog, same condition, completely different outcome based on timing.
What struck me reading through the fine print at Trupanion, Healthy Paws, Embrace, and Figo is how aggressively some insurers comb vet records for anything that could be labeled “pre-existing.” A single note mentioning “owner reports occasional limping” can exclude all orthopedic coverage. I’ve seen it happen to real clients. You go to insure your 4-year-old, they request medical records, they find a note from two years ago, and suddenly the thing most likely to go wrong with your breed is blocked out.
Insuring young, before anything gets documented, gives you the cleanest possible policy.
There’s also money involved. Most insurers won’t even enroll dogs over 14 years old, and premiums climb with age. Lock in coverage when your dog is young and you lock in lower premiums for life (Trupanion notably doesn’t raise rates based on age, only regional vet cost inflation).
What Insurance Actually Covers (and the Gaps You Need to Know About)
Most comprehensive accident and illness plans cover emergency care, surgeries, hospitalizations, diagnostic tests, specialist referrals, cancer treatment, and prescription medications. The good ones also cover hydrotherapy and acupuncture if recommended.
What they almost never cover: routine wellness visits, vaccines, flea prevention, dental cleanings (though dental disease requiring extraction sometimes gets covered), and elective procedures. Some companies sell “wellness add-ons.” Skip them. The math is almost always terrible, pricing at almost exactly what you’d get back.
The reimbursement model matters way more than people realize. Most insurers reimburse a percentage (70%, 80%, 90%) of the bill after deductible. Some use “usual and customary” rates instead of your actual bill, which leaves you holding more in high-cost cities or with specialists. Trupanion operates differently: they pay flat 90% of the invoice after deductible, no annual limits, no per-incident caps. For serious conditions, that difference is dramatic.
Annual limits are another gotcha. A policy with a $5,000 annual limit seems fine until your dog gets lymphoma and treatment costs $8,000 to $12,000. If your dog’s breed carries a known expensive condition (boxers and heart disease, golden retrievers and cancer, bernese mountain dogs and everything), an unlimited annual plan is worth paying extra for.
The Breeds Where This Becomes a Much Easier Decision
| Condition | Typical Surgery Cost Range | Common Breeds Affected |
|---|---|---|
| TPLO Surgery (cruciate ligament tear) | $3,500-$7,000 | Labs, golden retrievers, rottweilers, mixed breeds |
| Brachycephalic Obstructive Airway Surgery (BOAS) | $2,000-$5,000 | French bulldogs, bulldogs, brachycephalic breeds |
| Intervertebral Disc Disease Surgery | $8,000+ | Dachshunds, corgis |
| Bloat (GDV) Emergency Surgery | $3,000-$6,000 | Large and giant breeds |
| Foreign Body Ingestion Surgery | $2,000+ | All breeds |
| Cancer Treatment | $8,000-$12,000 | Golden retrievers, boxers, all breeds |
If you own a French bulldog, bulldog, or any brachycephalic breed, this isn’t philosophical. It’s financial planning you’d be foolish to skip. BOAS surgery runs $2,000 to $5,000 and is common. Intervertebral disc disease wrecks dachshunds and corgis; severe disc herniation surgery hits $8,000 or more. Large and giant breeds face bloat (GDV), which is a genuine six-hour emergency that often costs $3,000 to $6,000.
Mixed breeds do have lower risk for some heritable conditions. But they still eat rocks, tear cruciate ligaments, and get cancer. The “mutt discount” is real but not a free pass.
How to Actually Pick a Policy (Without Losing Your Mind)
Get quotes from at least Trupanion, Healthy Paws, and Embrace. Compare them side by side for your specific dog’s age, breed, and zip code. Don’t just look at monthly premium. Look at deductible structure (annual vs. per-incident matters), reimbursement percentage, and annual or lifetime maximum.
Choose a deductible you’d actually pay out of pocket. A $1,000 deductible lowers your premium but doesn’t help much on a $1,200 emergency visit.
Read the exclusions list before committing. Every policy has one. Look specifically for bilateral condition definitions. If your dog tears one cruciate ligament, some insurers will exclude the other knee as a pre-existing orthopedic condition going forward.
Buy it before your puppy’s first well visit if you can. There’s usually a brief waiting period (14 days for illness is standard; accidents often 3 to 5 days). You want zero documented health history when you enroll.
If cost is tight, an accident-only policy with a higher deductible is still better than nothing. Those run $15 to $25 a month for a young dog and catch the “dog ate something it shouldn’t have” emergencies that happen constantly.
And if you’re not buying insurance, put $100 a month into a dedicated pet emergency fund. The ASPCA Poison Control Center charges $95 just for a consultation when your dog eats something suspicious. Actual treatment on top of that adds up fast.
Pet insurance won’t make financial sense for every single owner in every situation. But an uninsured young dog is a financial liability you’re holding entirely yourself, and most people dramatically underestimate what a single bad week at the emergency vet costs. The time to think it through is before the corn cob, not after.
This article is for general informational purposes only and does not constitute veterinary advice. Pet health symptoms can have many causes and require professional evaluation. Always consult a licensed veterinarian for diagnosis and treatment specific to your pet.
Sources
- ASPCA Poison Control Center
- Zesty Paws Hip and Joint Supplement Chews for Dogs
- FRONTLINE Plus Flea and Tick Treatment for Dogs
- Nylabone Power Chew Durable Dog Chew Toys
- Dogs Devotion
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- EVERLIT 95-Piece Vet-Approved Pet First Aid Kit (~$32), Vet-approved 95-piece kit for dogs and cats, covers cuts, burns, sprains, and emergencies until you can reach a vet.
- Nutramax Cosequin DS Joint Supplement for Dogs (132ct) (~$36), The #1 veterinarian-recommended joint supplement brand, clinically studied for reducing joint pain in dogs.
- Certified Pet First Aid Kit with Guide Book (~$22), Certified pet first aid kit with step-by-step instructions, an essential item for every pet owner.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- EVERLIT 95-Piece Vet-Approved Pet First Aid Kit (~$32), Vet-approved 95-piece kit for dogs and cats, covers cuts, burns, sprains, and emergencies until you can reach a vet.
- Nutramax Cosequin DS Joint Supplement for Dogs (132ct) (~$36), The #1 veterinarian-recommended joint supplement brand, clinically studied for reducing joint pain in dogs.